Data atlas / commodity
Gold Against the US Dollar
A very accurate fit with a large positive skew. When volatility rises, gold tends to move higher.
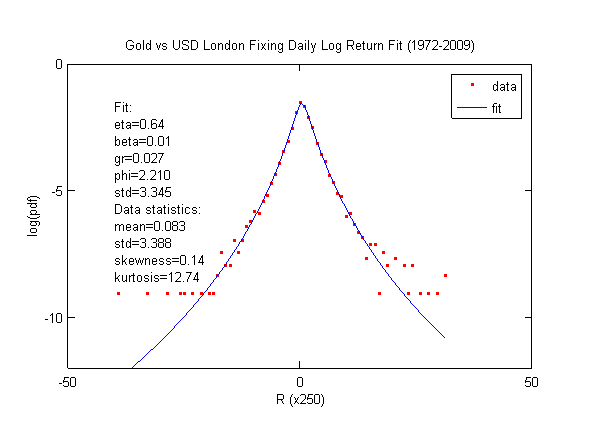
The fit is very accurate. Gold's kurtosis is large, and its return is skewed to the positive side. Whenever volatility rises, gold moves higher. This is similar to the VIX and opposite to the Dow.
The difference between the VIX and gold is that the VIX is mean reverting while gold is not. Higher gold prices tend to stick. The year 1972 is chosen because the link between gold and the US dollar changed at that point and gold began to fluctuate with large magnitude.
The gold volatility index is GVZ. Cboe started trading GVZ futures and options in March and April of 2011. Quotes have historically been displayed on Yahoo Finance.
Data source: LBMA London AM fixing.
Related fits
Compare the shape.
Source shelf
Data and further reading
- LBMA precious metal pricesLondon benchmark prices and market data.
- World Gold Council dataGold price data and market research.
- World Gold Council researchResearch on gold as a financial asset.
- Cboe GVZThe Cboe dashboard for the gold volatility index.
- Federal Reserve Economic DataEconomic time series from the Federal Reserve Bank of St. Louis.
- Lihn 2008 on SSRNThe 2008 working paper on the scale invariant Brownian motion model.
- Lihn 2009 on SSRNThe working paper on higher order lognormal cascade distributions.
- Clark 1973Subordinated stochastic process model for speculative prices.
- Fat tailed distributionsA reference overview of heavy tailed probability distributions.
- Lognormal distributionDefinition and properties of the lognormal distribution.
- Mandelbrot 1963The variation of certain speculative prices.
- Stochastic portfolio theoryA reference overview of stochastic portfolio theory.