Data atlas / stock index
Dow Weekly Log Return for 80 Years
Weekly sampling lowers the kurtosis, but the fat tailed shape remains. The fit has to trade kurtosis against variance.
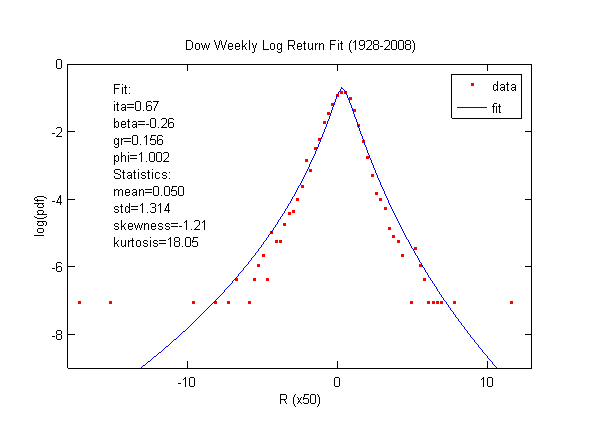
The Dow weekly log return has a smaller kurtosis than the daily return, but the kurtosis is still very significant. The general shape fits the skew lognormal cascade distribution well.
The fit has to choose between kurtosis and variance. They cannot be matched exactly at the same time. The version shown here weights kurtosis more heavily. The tradeoff is a fitted variance that is slightly larger than the sample variance.
Data source: Yahoo Finance.
Related fits
Compare the shape.
Source shelf
Data and further reading
- Yahoo FinanceMarket data and historical quotes used for several series.
- Nasdaq CompositeOfficial index information for the Nasdaq Composite.
- Nikkei marketsJapanese market data and index information from Nikkei.
- FTSE Russell US indicesIndex information for the Russell 2000 and related benchmarks.
- Federal Reserve Economic DataEconomic time series from the Federal Reserve Bank of St. Louis.
- Lihn 2008 on SSRNThe 2008 working paper on the scale invariant Brownian motion model.
- Lihn 2009 on SSRNThe working paper on higher order lognormal cascade distributions.
- Clark 1973Subordinated stochastic process model for speculative prices.
- Fernholz 2002Stochastic portfolio theory and the diversity index.
- Heavy tailed distributionsA reference overview of distributions with heavy tails.
- Lognormal distributionDefinition and properties of the lognormal distribution.
- Stochastic portfolio theoryA reference overview of stochastic portfolio theory.